
Black-Litterman Portfolio Optimization MCP Server
by irresi
README.md
# Black-Litterman Portfolio Optimization MCP Server
[](https://smithery.ai/server/@irresi/bl-view-mcp)
[](https://pypi.org/project/black-litterman-mcp/)
[](https://pypi.org/project/black-litterman-mcp/)
[](LICENSE)
**Black-Litterman portfolio optimization** MCP server for AI agents
Works with Claude Desktop, Windsurf IDE, Google ADK, and any MCP-compatible AI
## Features
- **Portfolio Optimization** - Black-Litterman model with sensitivity analysis
- **Investor Views** - Absolute/relative views with confidence levels
- **Backtesting** - Strategy comparison, drawdown analysis, timeseries
- **Asset Analysis** - Correlation matrix, VaR, per-asset statistics
- **Dashboard Generation** - Visualization hints for AI-generated charts
- **Multiple Assets** - S&P 500, NASDAQ 100, ETF, Crypto, custom data
---
## Quick Start
### Option 1: Smithery (Easiest - No Installation!) 🌟
Install via Smithery in one command:
```bash
npx @smithery/cli install @irresi/bl-view-mcp --client claude
```
Or visit [smithery.ai/server/@irresi/bl-view-mcp](https://smithery.ai/server/@irresi/bl-view-mcp) and click:
- **"Add to Claude Desktop"** - One-click setup
- **"Add to ChatGPT"** - Direct integration
- **"Run"** - Test in browser instantly
> **No Python/uv installation needed!** Smithery hosts the server for you.
### Option 2: Local Installation (uvx)
For offline use or development:
#### Step 1: Find uvx path
Run in terminal:
```bash
which uvx
# Example output: /Users/USERNAME/.local/bin/uvx
```
> If uvx is not installed: `curl -LsSf https://astral.sh/uv/install.sh | sh`
#### Step 2: Configure Claude Desktop
Config file location:
- **macOS**: `~/Library/Application Support/Claude/claude_desktop_config.json`
- **Windows**: `%APPDATA%\Claude\claude_desktop_config.json`
File content (replace with your uvx path):
```json
{
"mcpServers": {
"black-litterman": {
"command": "/Users/USERNAME/.local/bin/uvx",
"args": ["black-litterman-mcp"]
}
}
}
```
#### Step 3: Restart Claude Desktop
**Cmd+Q** (macOS) or fully quit and restart
---
## Usage
Ask Claude:
> "Optimize a portfolio with AAPL, MSFT, GOOGL. I think AAPL will return 10%."
> **First run**: S&P 500 data auto-downloads (~30 seconds)
> **Tip**: Want charts or dashboards? Just ask: "Show me a dashboard with the results" or "Create a visualization of the portfolio weights"
### Example Use Cases
Try these prompts with Claude:
> **Note**: Default period is **1 year** for all tools. All returns are **annualized** - when you say "outperform by 40%", it means 40% annual return expectation.
**Basic Optimization + Visualization**
> Optimize a portfolio with AAPL, MSFT, GOOGL, NVDA. I am confident that NVDA will outperform others by 40%. Show me a dashboard.
**Backtesting with Benchmark**
> Backtest the above optimized portfolio for 3 years and compare with SPY.
**Strategy Comparison**
> Compare buy_and_hold, passive_rebalance, and risk_managed strategies for this portfolio.
**Correlation Analysis**
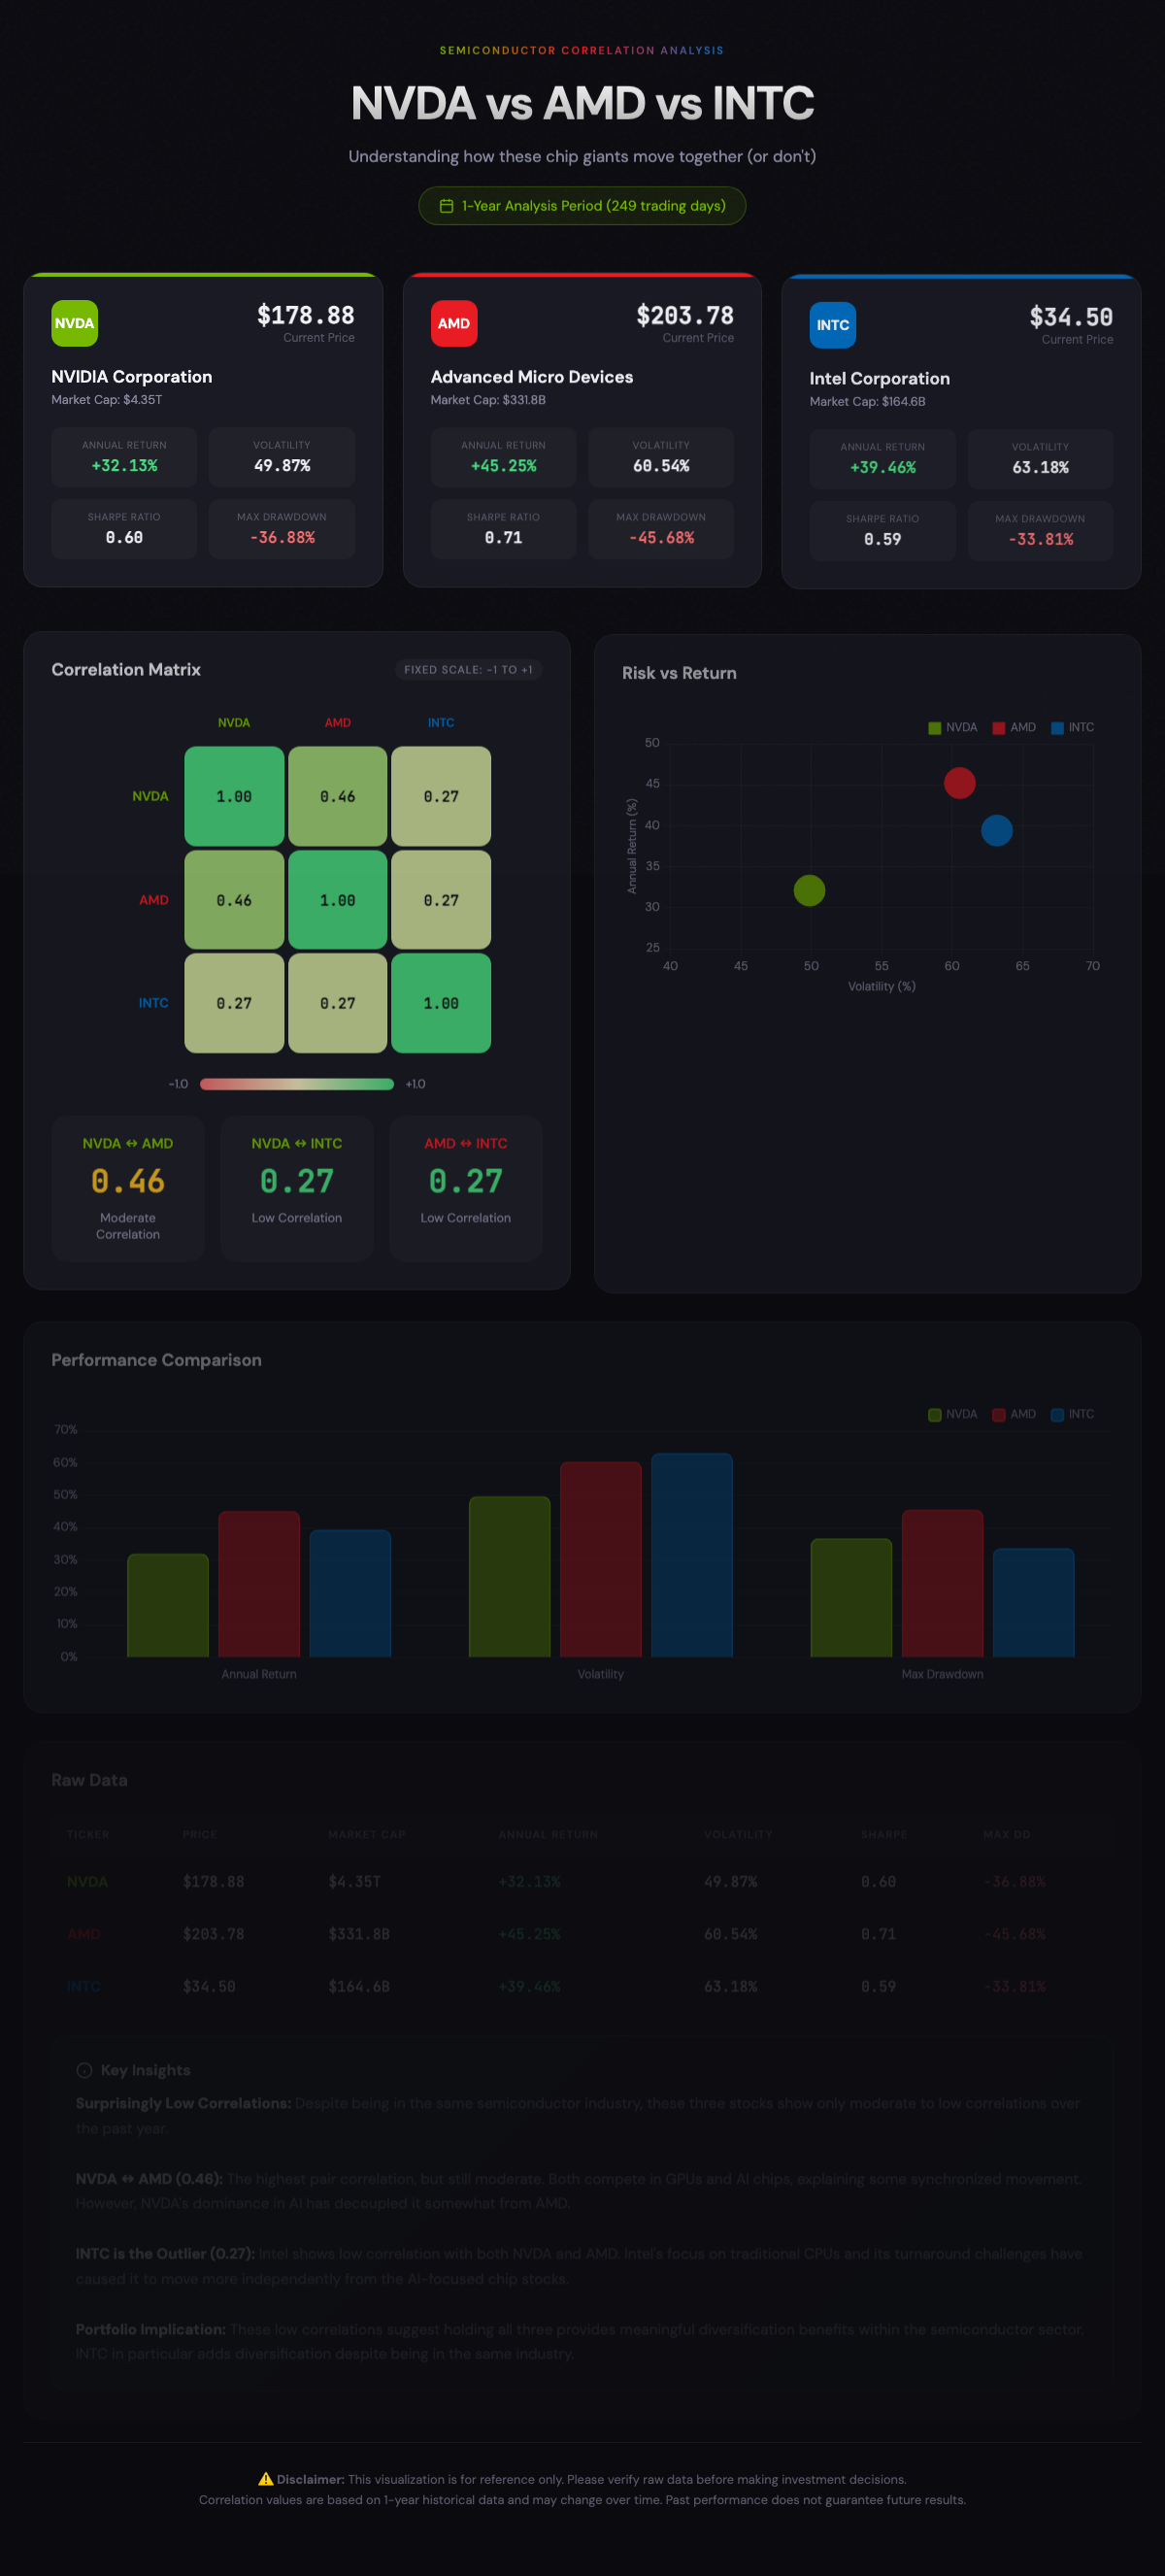
> Analyze the correlation between NVDA, AMD, and INTC.
**Sensitivity Analysis**
> Create a portfolio with AAPL and MSFT. I expect AAPL to return 15%. Run sensitivity analysis with confidence levels 0.3, 0.5, 0.7, 0.9.
### Demo Dashboards
Generated using the example prompts above with Claude Desktop:
<ins>Click images</ins> to view interactive HTML dashboards:
| Optimization | Backtest | Strategy |
|:---:|:---:|:---:|
| [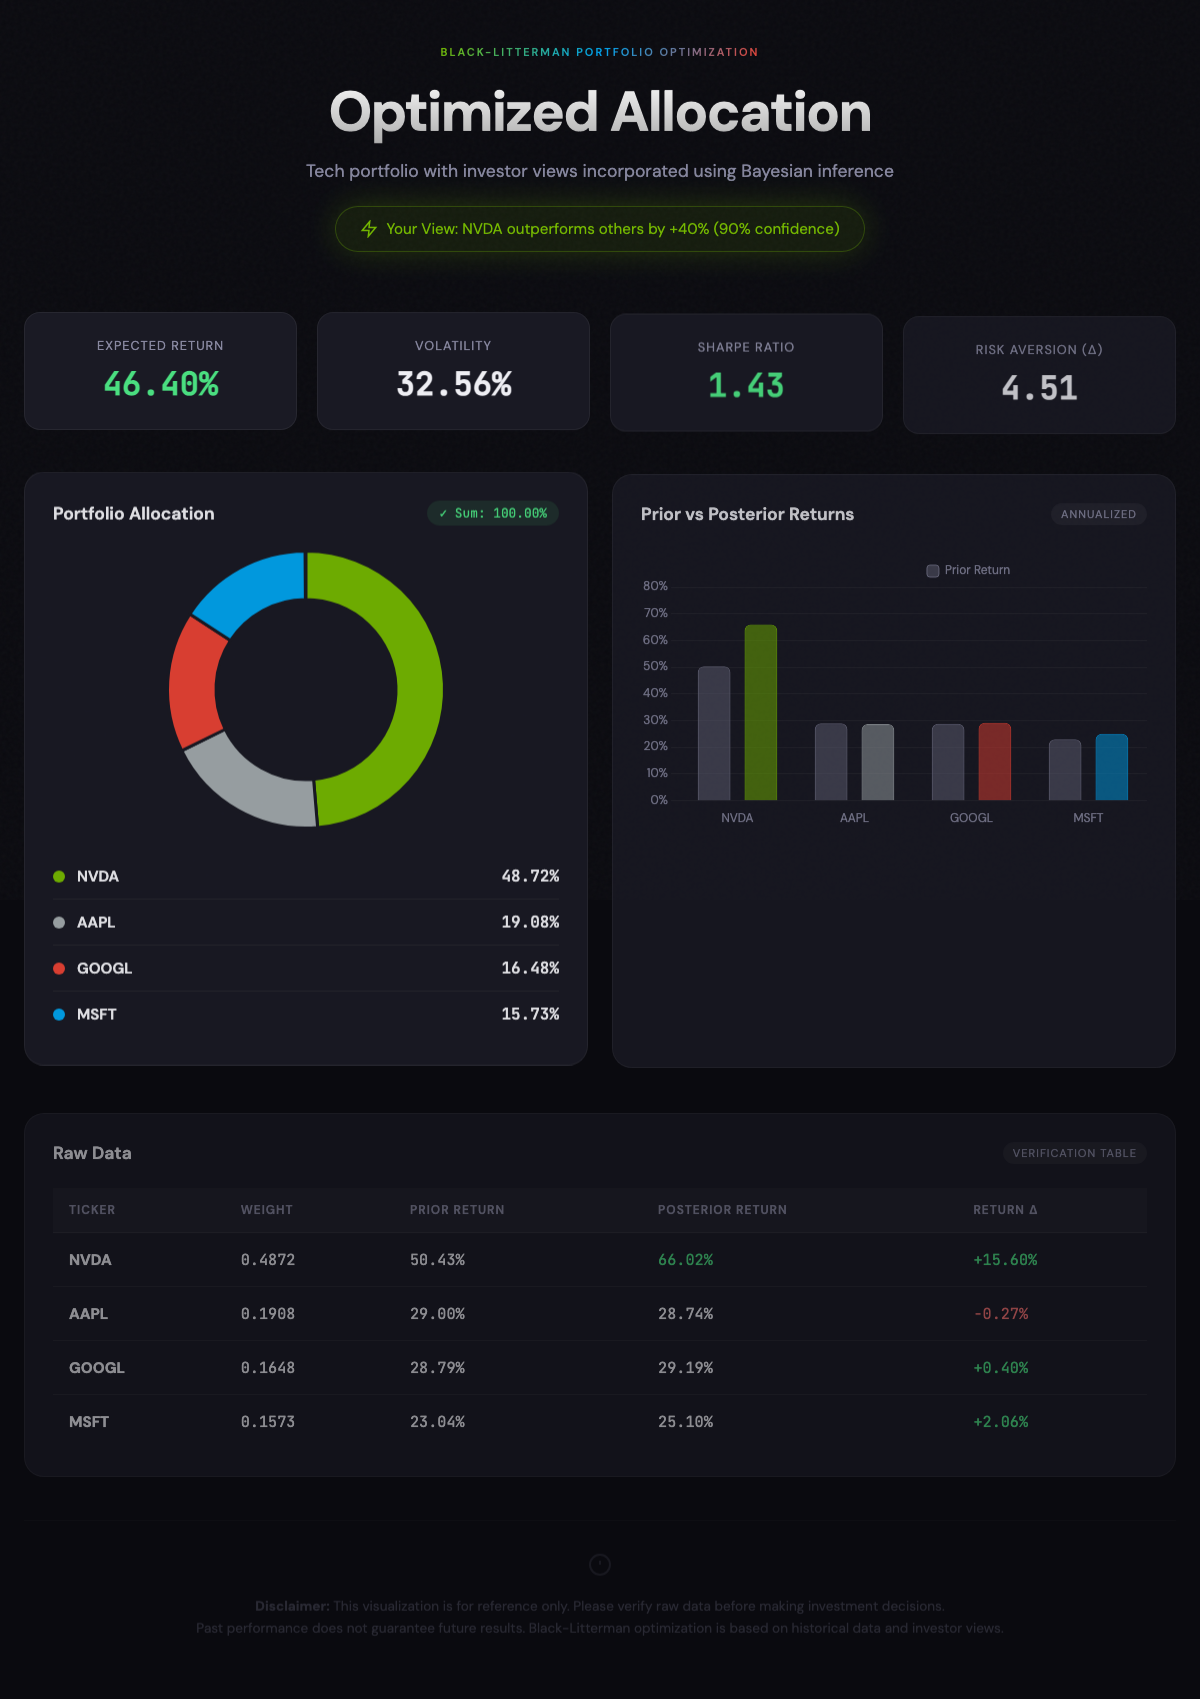](https://irresi.github.io/bl-view-mcp/examples/dashboards/demo_optimization.html) | [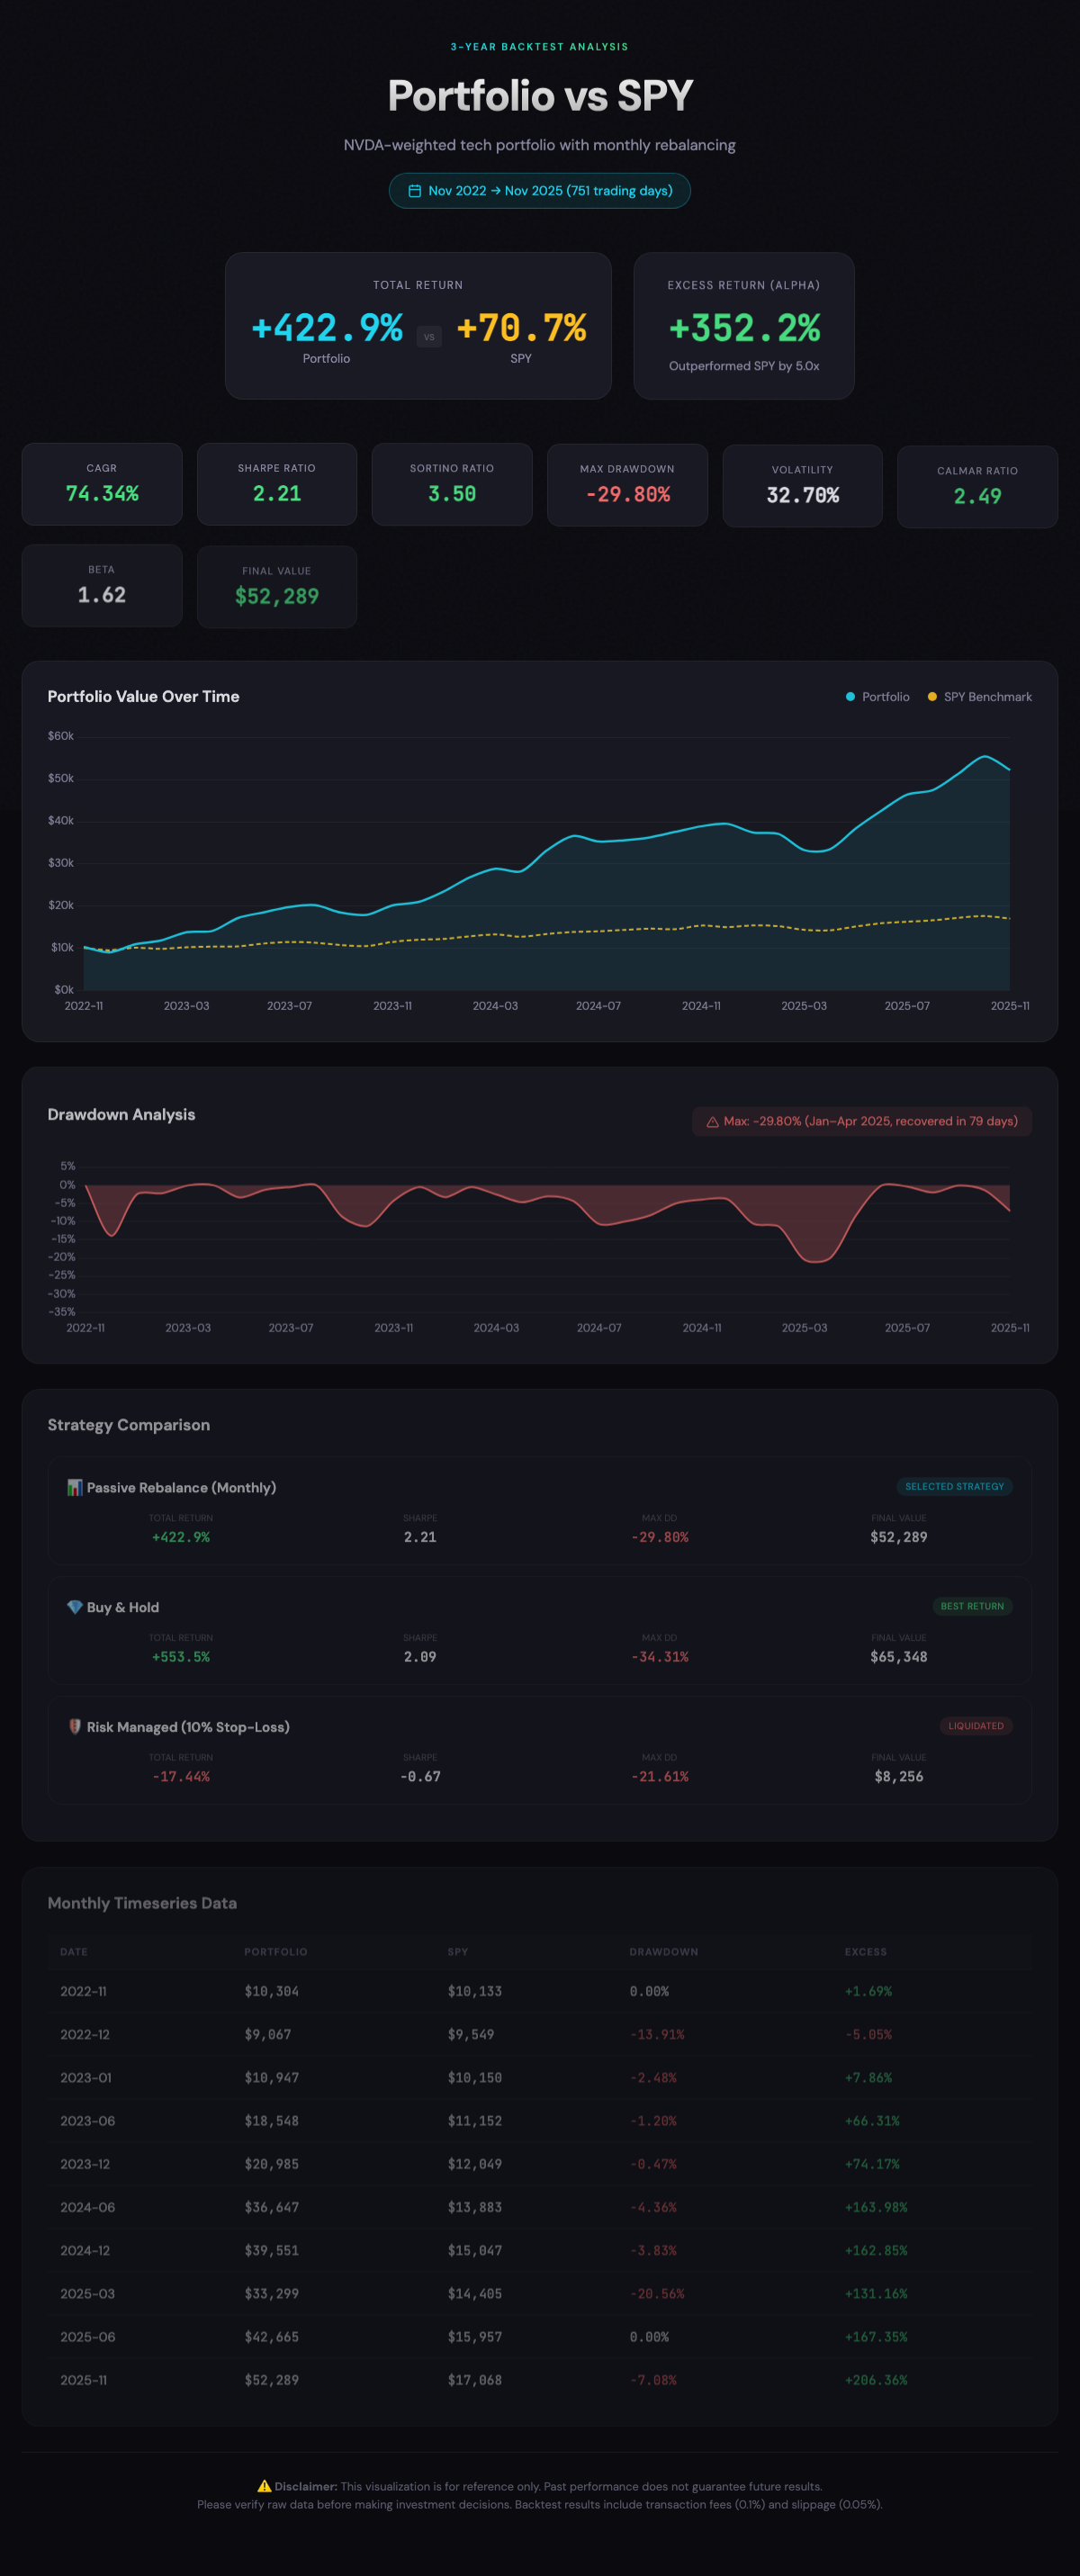](https://irresi.github.io/bl-view-mcp/examples/dashboards/demo_backtest.html) | [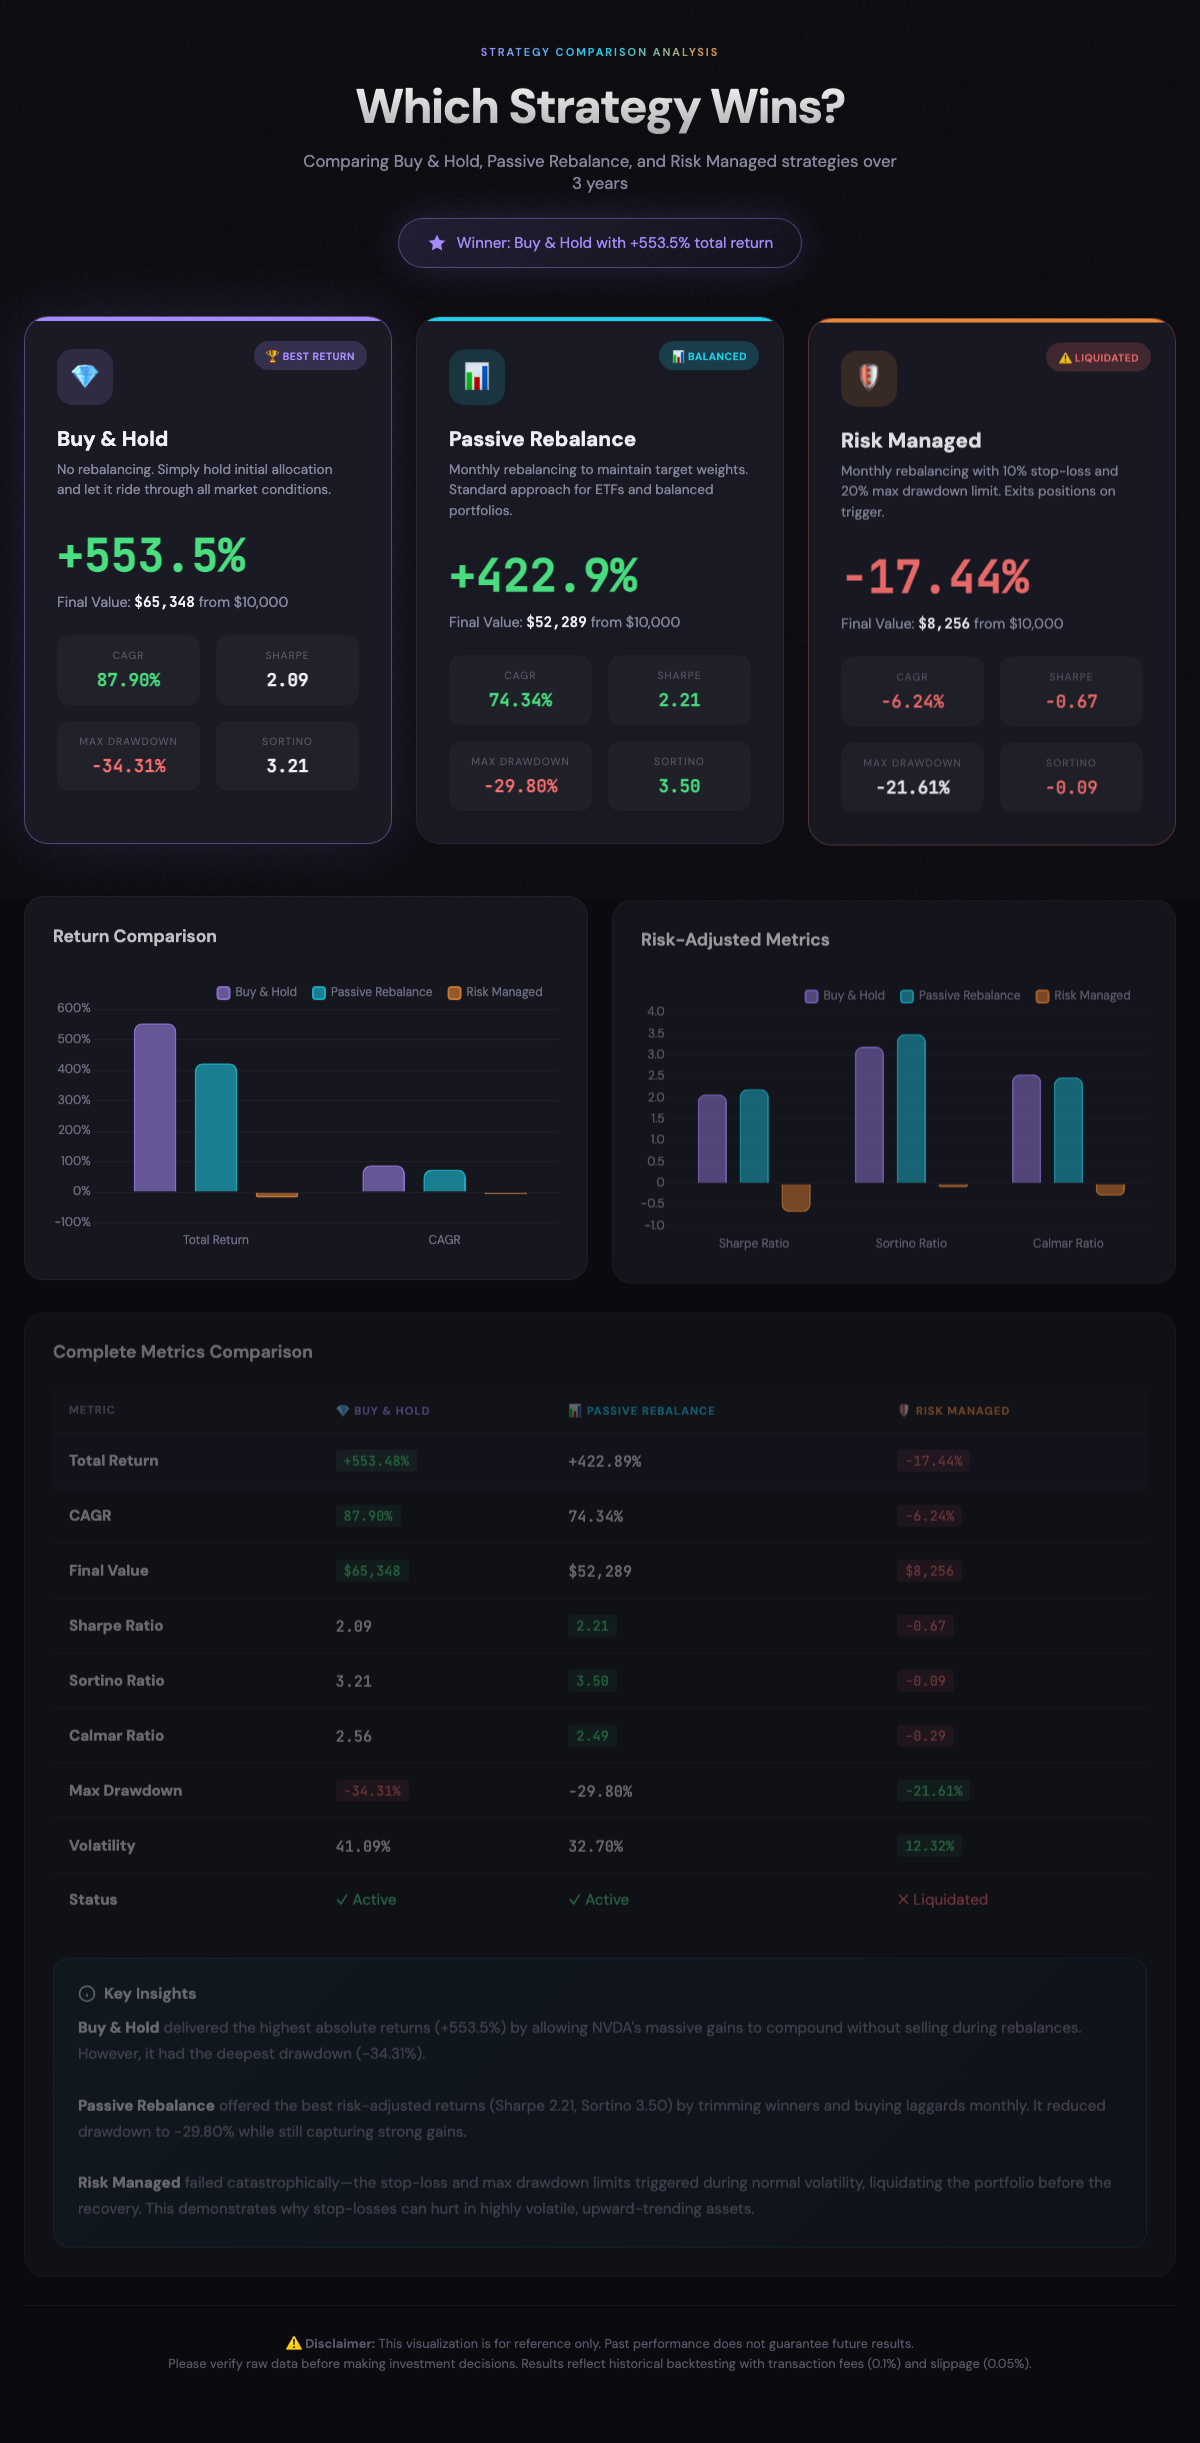](https://irresi.github.io/bl-view-mcp/examples/dashboards/demo_strategy.html) |
| Correlation | Sensitivity |
|:---:|:---:|
| [](https://irresi.github.io/bl-view-mcp/examples/dashboards/demo_correlation.html) | [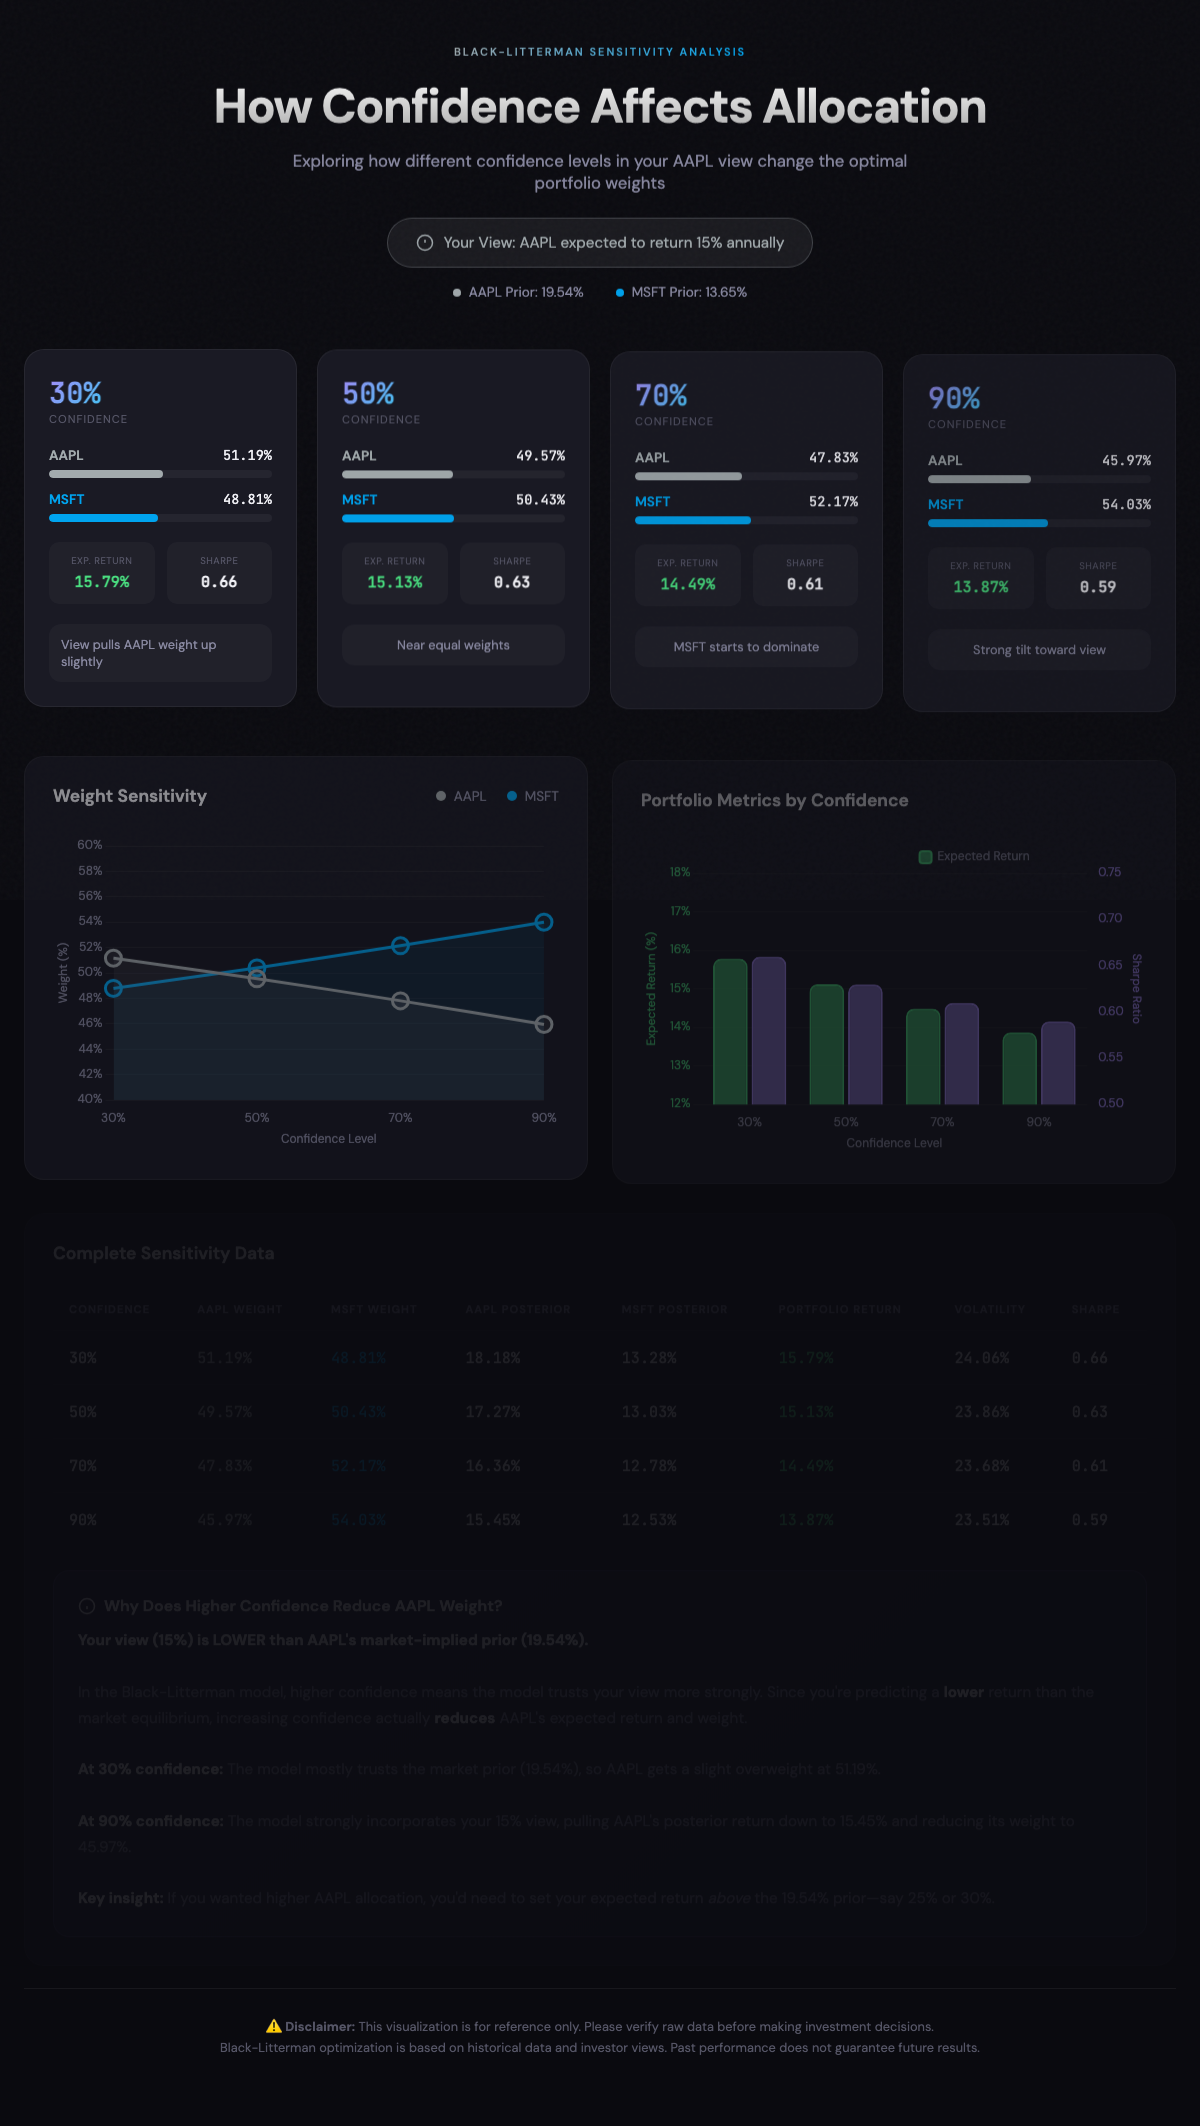](https://irresi.github.io/bl-view-mcp/examples/dashboards/demo_sensitivity.html) |
---
## Other Installation Methods
### pip (Python Package)
Install directly from PyPI:
```bash
pip install black-litterman-mcp
```
Then configure your MCP client to run:
```bash
black-litterman-mcp # or bl-view-mcp, bl-mcp
```
> Requires Python 3.11+. Data auto-downloads on first use.
### Windsurf IDE
`.windsurf/mcp_config.json`:
```json
{
"mcpServers": {
"black-litterman": {
"command": "/Users/USERNAME/.local/bin/uvx",
"args": ["black-litterman-mcp"]
}
}
}
```
### From Source (Developers)
```bash
git clone https://github.com/irresi/bl-view-mcp.git
cd bl-view-mcp
make install
make download-data # S&P 500 data
make test-simple
```
### Docker
```bash
docker build -t bl-mcp .
docker run -p 5000:5000 -v $(pwd)/data:/app/data bl-mcp
```
### Google ADK Web UI
Test with [Google ADK](https://github.com/google/adk-python) (Agent Development Kit):
```bash
# Terminal 1: Start MCP HTTP server
make server-http # localhost:5000
# Terminal 2: Start ADK Web UI
make web-ui # localhost:8000
```
Open http://localhost:8000 in browser
> Requires `make install` (includes google-adk dependency)
---
## Supported Datasets
| Dataset | Tickers | Description |
|---------|---------|-------------|
| `snp500` | ~500 | S&P 500 constituents (default) |
| `nasdaq100` | ~100 | NASDAQ 100 constituents |
| `etf` | ~130 | Popular ETFs |
| `crypto` | ~100 | Cryptocurrencies |
| `custom` | - | User-uploaded data |
**PyPI install**: S&P 500 data auto-downloads on first run
**Source install**: Download additional datasets manually
```bash
make download-data # S&P 500 (default)
make download-nasdaq100 # NASDAQ 100
make download-etf # ETF
make download-crypto # Crypto
```
---
## MCP Tools
### `optimize_portfolio_bl`
Calculate optimal portfolio weights using Black-Litterman model.
```python
optimize_portfolio_bl(
tickers=["AAPL", "MSFT", "GOOGL"],
period="1Y",
views={"P": [{"AAPL": 1}], "Q": [0.10]}, # AAPL expected 10% return
confidence=0.7,
investment_style="balanced" # aggressive / balanced / conservative
)
```
**Views examples**:
```python
# Absolute view: "AAPL will return 10%"
views = {"P": [{"AAPL": 1}], "Q": [0.10]}
# Relative view: "NVDA will outperform AAPL by 20%"
views = {"P": [{"NVDA": 1, "AAPL": -1}], "Q": [0.20]}
```
**VaR Warning**: When predicted returns exceed 40%, EGARCH-based VaR analysis is automatically included in the `warnings` field.
### `backtest_portfolio`
Validate portfolio strategy with historical data.
```python
backtest_portfolio(
tickers=["AAPL", "MSFT", "GOOGL"],
weights={"AAPL": 0.4, "MSFT": 0.35, "GOOGL": 0.25},
period="3Y",
strategy="passive_rebalance", # buy_and_hold / passive_rebalance / risk_managed
benchmark="SPY"
)
```
### `get_asset_stats`
Get asset statistics including VaR, correlation matrix, and covariance matrix.
```python
get_asset_stats(
tickers=["AAPL", "MSFT", "GOOGL"],
period="1Y",
include_var=True # Set False for faster response (skips EGARCH VaR)
)
# Returns: assets (price, return, volatility, sharpe, var_95, percentile_95),
# correlation_matrix, covariance_matrix
```
### `upload_price_data`
Upload external data (international stocks, custom assets, etc.).
```python
# Direct upload (small data)
upload_price_data(
ticker="005930.KS", # Samsung Electronics
prices=[
{"date": "2024-01-02", "close": 78000.0},
{"date": "2024-01-03", "close": 78500.0},
...
],
source="custom"
)
# Or load from file (large data)
upload_price_data(
ticker="CUSTOM_INDEX",
file_path="/path/to/data.csv",
date_column="Date",
close_column="Close"
)
```
### `list_available_tickers`
Query available tickers.
```python
list_available_tickers(search="AAPL") # Search
list_available_tickers(dataset="snp500") # S&P 500 only
list_available_tickers(dataset="custom") # Custom data
```
---
## Documentation
| Document | Description |
|----------|-------------|
| [docs/TESTING.md](docs/TESTING.md) | Testing guide |
| [docs/ARCHITECTURE.md](docs/ARCHITECTURE.md) | Technical architecture |
---
## Tech Stack
- **MCP Server**: [FastMCP](https://github.com/jlowin/fastmcp)
- **Optimization**: [PyPortfolioOpt](https://github.com/robertmartin8/PyPortfolioOpt)
- **Risk Model**: [arch](https://github.com/bashtage/arch) (EGARCH)
- **Data**: yfinance, ccxt (crypto)
---
## License
MIT License - [LICENSE](LICENSE)
---
## Troubleshooting
### "spawn uvx ENOENT" / "uv binary not found"
Claude Desktop may not recognize system PATH. Use **absolute path**:
```bash
which uvx
# Use the output path in config
```
### "Data file not found"
Source install:
```bash
make download-data
```
PyPI install: Auto-downloads on first run (~30 seconds).
### "uv: command not found"
```bash
curl -LsSf https://astral.sh/uv/install.sh | sh
```
### Need more help?
- [GitHub Issues](https://github.com/irresi/bl-view-mcp/issues)This server cannot be deployed
Maintenance
ActivityInactive
ResponsivenessNo issues